How to Help a Child Build a Savings Goal: The Art of Wanting Something Tomorrow
Teaching kids to save money starts with a dream, not a number. Discover how small choices, patience, and playful goals help children build healthy financial habits that last a lifetime.
Teaching children to save isn't really about money. It's about helping them discover that some of the best things in life are worth waiting for, and that even the smallest choices can bring a distant dream a little closer.
There is a particular kind of excitement that belongs to childhood. It begins with the discovery of something wonderful: a bicycle glimpsed through a shop window, a new game discussed endlessly with friends, a telescope that promises to bring the moon into the bedroom, or perhaps a small collection of objects whose importance is entirely incomprehensible to the adults in the house. The desire arrives suddenly, occupies every available corner of the imagination, and demands an immediate answer. To a child, tomorrow is a distant country, next month an almost geological era, and the possibility of waiting several weeks for something they want can seem genuinely unreasonable. Yet somewhere inside that impatience lies one of the most valuable lessons we can teach about money: wanting something and obtaining it do not have to happen at the same moment.
Most adults understand this principle intellectually, although our own purchasing habits suggest that we have not entirely mastered it. We save for holidays, postpone replacing appliances, compare prices before making important purchases, and occasionally buy something we never intended to buy because it was beautifully displayed or temporarily discounted. Children are not fundamentally different. They simply have less experience negotiating the distance between desire and satisfaction. Helping them build a savings goal is an opportunity to explore that distance together, without turning childhood into a miniature financial management course or transforming every coin into a moral examination.
The objective is not to raise children who never spend money. It is to help them discover that money can do more than disappear in exchange for something attractive. It can carry an intention forward through time.
A Goal Begins With a Story, Not a Number
Imagine a nine-year-old who announces that they absolutely need a new skateboard. They have seen one at the park, watched videos of impressive tricks, and already pictured themselves gliding effortlessly along the pavement. The skateboard costs €60, which might represent several weeks of pocket money or a contribution from a birthday present. An adult might immediately begin calculating how much needs to be saved each week, but the most useful first question is not mathematical.
It is simply: "What makes you want this skateboard?"
The answer matters because a savings goal without emotional meaning is just an exercise in subtraction. Perhaps the child wants to join friends at the skatepark. Perhaps they are fascinated by learning a difficult skill. Perhaps they simply love the colourful design. All these motivations deserve to be heard, even when we suspect the enthusiasm might fade before the purchase becomes possible. A child who feels that their desire has been understood is more likely to engage with the practical decisions required to pursue it.
This is also where parents can introduce a distinction that will remain useful throughout adult life: the difference between the object we want and the experience we hope it will provide. We do not always want a bicycle merely because it has two wheels. Sometimes we want independence, adventure, or the freedom to follow our friends somewhere new. Understanding what sits behind a purchase can reveal alternatives, help us compare different options, and occasionally show us that the most expensive solution is not necessarily the most satisfying.
There is no need to interrogate every childhood wish with philosophical seriousness. A child is allowed to want a ridiculous toy simply because it is ridiculous. But when a wish becomes a savings goal, it deserves a little more attention than a price tag.
Turn the Dream Into Something You Can See
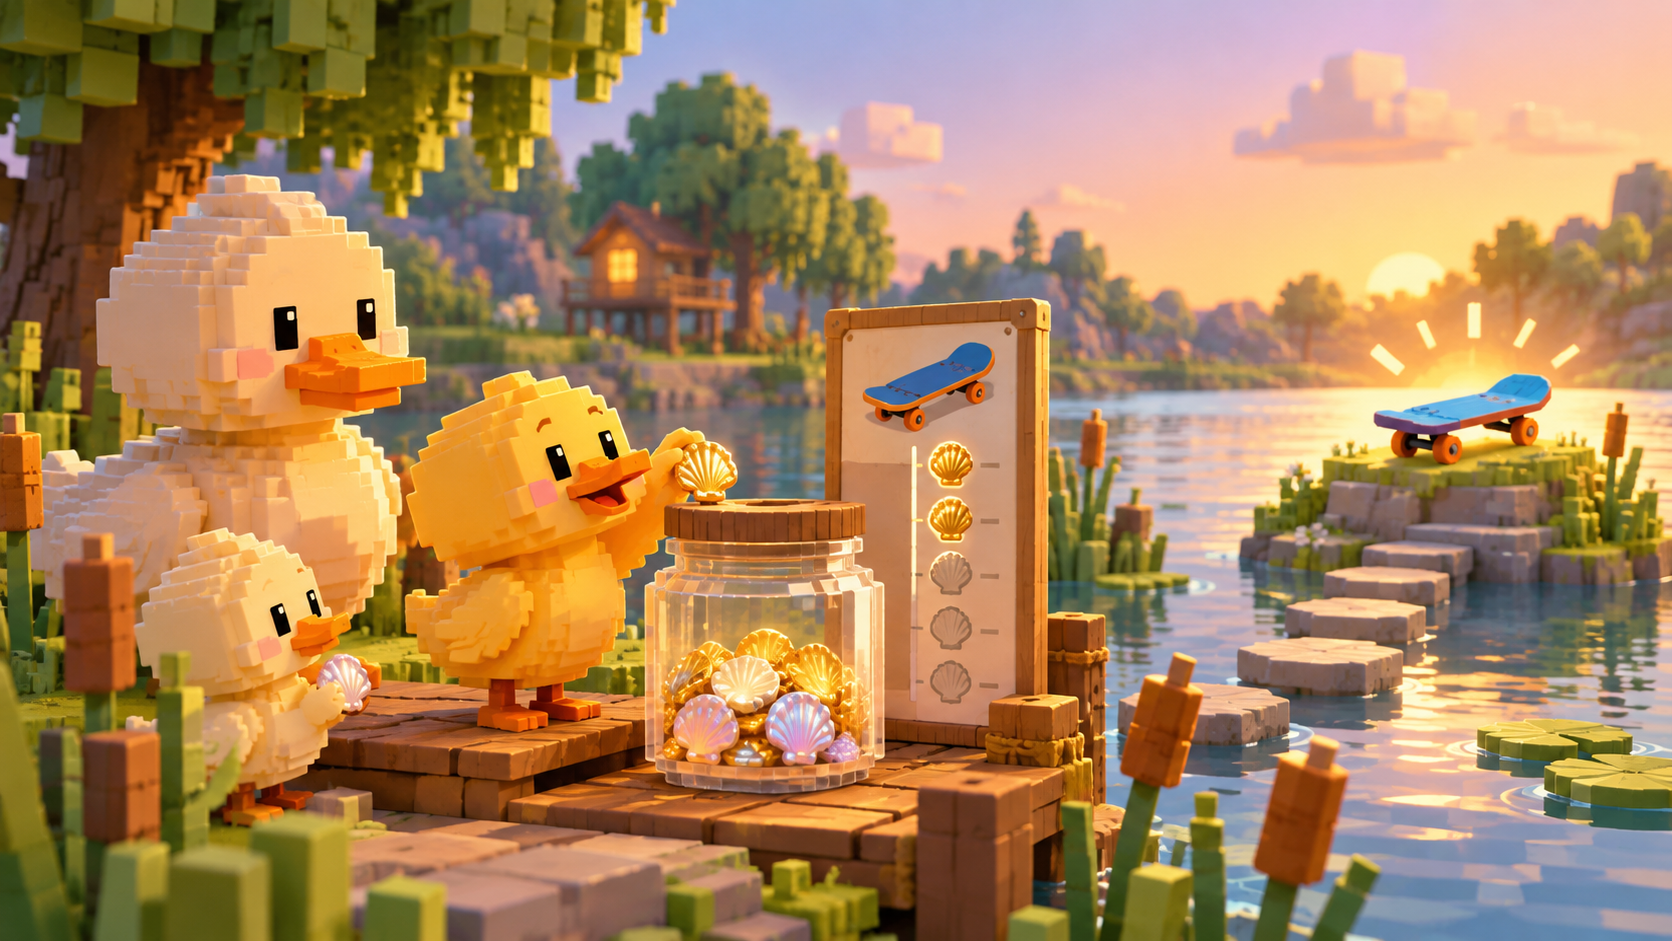
Once the goal has been chosen, money needs to become visible. This is particularly important for younger children, for whom numbers in a bank account can feel almost as abstract as distances between planets. A physical jar, a drawing divided into sections, a progress chart on the refrigerator, or a digital representation of accumulated savings can transform an invisible financial process into something concrete.
Suppose our aspiring skateboarder receives €8 each week and decides to save €5 of it. Reaching €60 would take twelve weeks, assuming they start from zero and receive no additional contributions. Twelve weeks may sound terribly long to a nine-year-old, but twelve small milestones are easier to imagine. After the first week, one part of the picture can be coloured. After the fourth, a third of the journey is complete. By the eighth week, the skateboard is no longer an impossible object in a shop window but an increasingly realistic destination.
The important transformation is psychological. Instead of experiencing saving as a repeated act of losing €5 that could have been spent immediately, the child begins to experience it as progress towards something meaningful. Every contribution changes the picture. Every small decision has a visible consequence.
This is one of the ideas behind YOBY, where financial concepts are explored through a playful world of ducks, ponds, characters, and choices. When progress can be experienced rather than merely calculated, money becomes easier to discuss, particularly for children who are only beginning to understand its relationship with time.
A savings chart does not need to be sophisticated, and a digital world does not need to resemble an adult budgeting application. The principle is the same: make the future tangible enough that a child can feel they are moving towards it.
The Secret Is Not Saving Everything
One of the easiest mistakes adults make when teaching children to save is treating spending as a failure. If a child has decided to accumulate money for a bicycle, every chocolate bar or inexpensive toy purchased along the way can begin to look like a small betrayal of the original plan. Parents may be tempted to point out that without those unnecessary purchases the bicycle would arrive sooner, and mathematically they would be correct. Educationally, however, the lesson might become rather less useful.
A child who learns that saving means never enjoying their money may eventually decide that saving is simply not much fun.
A better approach is to give money different purposes. Our skateboarder might save €5 from an €8 weekly allowance while keeping €3 available for immediate pleasures. They can buy a snack, contribute to a small outing, or spend the entire amount on a wonderfully pointless novelty. These choices are not interruptions to financial education. They are financial education.
The child begins to understand that money is limited, but choices remain possible within those limits. Saving for something important does not require abandoning every smaller pleasure. It requires deciding how much of today's money should belong to tomorrow.
This balance also helps avoid an unfortunate association between financial responsibility and guilt. Adults are frequently told that buying a coffee or enjoying a modest treat is evidence of poor discipline. Children deserve a healthier introduction to money. There is nothing inherently irresponsible about spending, just as there is nothing inherently virtuous about saving. Both become useful when connected to intentions, circumstances, and consequences.
The real skill is not always choosing the future over the present. It is learning that we have a choice.
When the Shiny Thing Appears Along the Way
Of course, no savings journey proceeds through a perfectly orderly landscape. Somewhere around the third or fourth week, another object will appear. Perhaps it is a trading card set, a new toy, or an accessory that everyone at school seems to possess. It costs €15, and our skateboarder already has €20 saved. Suddenly the original goal faces its first serious competition.
This moment is more educational than the previous weeks of flawless saving.
Parents can respond by reminding the child of their commitment, but there is a difference between reminding someone of a goal and making the decision for them. Rather than forbidding the purchase, we might ask what would happen to the skateboard plan if €15 were spent today. How many additional weeks would be needed? Would the new object still seem as exciting after a few days? Is there another way to obtain something similar for less?
The purpose of these questions is not to manipulate the child towards the answer we prefer. It is to make the trade-off visible.
If the child chooses to buy the trading cards, the savings goal may move further away. That is a consequence, not a catastrophe. They may regret the decision later, or they may enjoy the cards enormously and consider the purchase worthwhile. Either outcome provides an opportunity to understand the relationship between choices and priorities.
One useful family habit is to introduce a short waiting period for unplanned purchases above an agreed amount. It might be a day, a weekend, or simply until the next allowance arrives. The waiting period should not feel like punishment. It creates a little breathing room between discovering something desirable and deciding whether to buy it.
Sometimes the desire survives. Sometimes it evaporates overnight. Learning to recognise the difference is a skill that will remain valuable long after the skateboard has been forgotten.
What If the Child Changes Their Mind?
Adults are surprisingly attached to consistency. We admire determination, celebrate perseverance, and frequently encourage children to finish what they started. These are valuable qualities, but they can become problematic when applied indiscriminately to financial goals.
Imagine that after six weeks of saving, our skateboarder discovers a genuine passion for astronomy. The skateboard is still an interesting possibility, but a small telescope now occupies the centre of their imagination. Should they be required to continue saving for the skateboard because that was the original agreement?
Not necessarily.
Changing a goal can be a sign of growing understanding rather than a failure of commitment. Adults revise financial plans all the time. We change our holiday destinations, postpone purchases, redirect savings towards unexpected needs, and discover that yesterday's priorities no longer reflect today's circumstances. Children need to learn this flexibility too.
The distinction worth discussing is between a thoughtful change of direction and a succession of impulsive decisions. Has the child discovered a new interest that seems likely to last? Have they considered the cost and alternatives? Can they explain why the new goal matters more than the old one? If so, adjusting the plan may be entirely reasonable.
Parents can help by making the change deliberate. The savings already accumulated remain visible, the new target is calculated, and the child sees how their previous efforts contribute to the revised objective. Nothing has been wasted. Money saved for one purpose does not lose its value when that purpose changes.
In fact, this may be one of the most empowering discoveries of all: savings create possibilities. They give us room to change our minds.
The Role of Parents: Companions, Not Financial Inspectors
Children learn an extraordinary amount about money without ever receiving a formal explanation. They notice when adults worry about prices, argue over purchases, compare supermarket offers, or celebrate finally being able to afford something important. They observe our habits long before they understand our reasoning, and their earliest ideas about financial behaviour are often assembled from these scattered domestic scenes.
This makes parents influential teachers, but it does not mean they need to become perfect financial role models. A family can teach valuable lessons about saving while experiencing its own difficulties, making mistakes, or trying to improve established habits.
One particularly effective way to make saving a shared activity is to let children see adults working towards goals of their own. Perhaps the family is putting money aside for a holiday, replacing an old television, or planning a weekend excursion. The amounts and responsibilities will naturally be different, but the underlying process is recognisable: we want something, we decide what matters, and we make small choices that move us closer.
Children do not need access to private financial information or the burden of adult money worries. They simply benefit from understanding that saving is something people do throughout their lives, rather than a peculiar discipline invented to prevent children from buying toys.
A parent might explain that the family has decided to cook at home this weekend because they are saving for a special trip. Another day, they might openly acknowledge choosing a spontaneous treat instead. These everyday conversations communicate something more valuable than an idealised picture of financial perfection. They show that managing money involves judgment, compromise, and priorities.
The same principle works when children struggle with their own goals. Instead of asking why they failed to save, we can ask what made the decision difficult. Instead of rewarding only successful outcomes, we can notice the effort involved in planning, reconsidering, and trying again.
Financial confidence grows more easily in an atmosphere of curiosity than under constant inspection.
Different Ages, Different Horizons
A six-year-old and a thirteen-year-old do not experience time, ownership, or responsibility in the same way. Expecting them to approach savings goals with identical methods would be as strange as giving them the same reading material and assuming they would learn equally well.
Younger children generally benefit from immediate, highly visible goals. Saving a few coins towards a small toy or an inexpensive book can offer a complete experience of planning and achievement within a manageable period. If the objective is too distant, the connection between today's decision and tomorrow's reward may simply disappear. At this stage, handling coins, filling a jar, and celebrating milestones can be more meaningful than mastering percentages or financial terminology.
As children grow, goals can become more ambitious. A nine- or ten-year-old might enjoy tracking weekly progress towards a purchase that requires several months of patience. They can begin comparing prices, considering second-hand alternatives, and discussing what happens if their saving rate changes. These activities introduce basic arithmetic in a context where the numbers genuinely matter to them.
Older children and early teenagers can explore more complex decisions. They may want to save for a device, a hobby, a trip, or an activity that involves additional costs beyond the initial purchase. This creates an opportunity to discuss maintenance, subscriptions, replacement parts, and other expenses that are not always visible on a price tag. A gaming console, for example, may be affordable on the day of purchase while the games and accessories that follow require further planning.
These age distinctions are useful starting points, not rigid developmental rules. Children differ in experience, attention, and interest. What matters is choosing a goal that feels meaningful and challenging without becoming discouraging.
The best financial lesson is rarely the most complicated one. It is the one a child can connect to a decision they actually care about.
Celebrate the Journey Before Celebrating the Purchase
Eventually, if our skateboarder remains committed, the twelfth week arrives. The money has been saved, the skateboard can be purchased, and a small celebration is certainly appropriate. But it would be a shame if the entire experience were reduced to the object itself.
The more interesting achievement is what happened along the way.
The child identified something important, transformed a wish into a plan, divided a large objective into smaller steps, resisted some temptations, perhaps surrendered to others, and discovered that decisions made several weeks apart could contribute to a single outcome. They experienced the unfamiliar pleasure of obtaining something not immediately, but through a process they understood and influenced.
That experience deserves recognition independently of the purchase.
We might ask which part of the journey was hardest, whether the waiting changed how they felt about the skateboard, and what they would do differently next time. We might also discover that the object is less exciting than expected. This possibility should not be treated as a disaster. Sometimes the anticipation of a purchase exceeds the satisfaction it eventually provides, and recognising that difference is itself a remarkable financial insight.
There is another possibility worth remembering. The child might reach their goal and decide not to buy the skateboard at all. Now that the money is available, keeping it offers an attractive sense of freedom. What began as a desire for an object has become an appreciation of having options.
That is not an unsuccessful savings goal. It may be the most interesting outcome imaginable.
A Small Family Experiment Worth Trying
If you want to introduce savings goals at home, begin with a conversation rather than a rule. Invite your child to choose something they would genuinely enjoy obtaining, preferably something within a realistic saving horizon. Find out what it costs, explore whether there are alternatives, and agree on a manageable contribution from whatever money they normally receive or have available.
Give the goal a visible representation and make progress easy to observe. A drawing, a jar, or a playful digital environment can all serve the purpose. Allow room for spending along the way, and resist the temptation to turn every small purchase into a lecture about discipline. Check on the goal occasionally, not as an examination, but as something worth discussing together.
Most importantly, let the experience belong to the child. Parents can offer advice, help with calculations, and explain consequences, but the educational value becomes much greater when children have genuine opportunities to choose.
Not every family uses pocket money, and not every household can comfortably set money aside. A savings experiment should never become a measure of financial privilege. It can begin with birthday money, small gifts, symbolic tokens, or a shared family goal that does not require the child to contribute financially. The concepts of planning, patience, and choosing between alternatives can be explored in many ways, including through play.
What matters is the relationship between a decision made today and a possibility created tomorrow.
Why We Believe Financial Education Should Feel Like Play
At YOBY, we believe children understand money more naturally when they can explore it rather than merely hear explanations about it. Saving is an especially good example because it connects so many different ideas: patience, priorities, decision-making, opportunity cost, and the satisfaction of gradual progress. Yet none of these concepts needs to arrive wrapped in technical vocabulary.
A child can learn about saving by helping a duck reach an imaginary destination, deciding whether to spend symbolic currency at a market, or watching a goal move closer through a series of small choices. A character can ask an unexpected question, a decision can produce a visible consequence, and a parent can join the conversation without needing to deliver a lesson.
The playful setting does not make the underlying ideas less serious. It makes them easier to encounter, discuss, and remember. And when children and parents explore these situations together, financial education becomes something more than the transfer of information from one generation to another. It becomes a shared language for talking about desires, limits, possibilities, and the future.
Perhaps that is the most important reason to help a child build a savings goal. The coins themselves are temporary. The skateboard will eventually wear out, the toy may be forgotten, and the treasured object of today may become tomorrow's archaeological discovery at the bottom of a cupboard. But the understanding that a distant possibility can be approached through a succession of small, intentional choices can remain for decades.
Saving is not simply learning to say no to something today. It is learning that today's money can have a tomorrow, and that we have a say in what that tomorrow looks like.
At YOBY, children and families explore money through playful choices, curious characters, and a world of ducks where financial habits can grow one small decision at a time. Because learning about money should begin with curiosity, not anxiety.